By Bobby Garon
Insurance basics tend to get avoided until something forces the conversation, a new house, a new baby, a scare that makes someone realize they never actually read their policy. Here in Naples, Florida, I sit down with people at every one of those moments, and I’ve noticed the same thing almost every time. Most people are paying for insurance without fully understanding what it does or when it actually kicks in. I touched on some of these ideas recently in a financial planning masterclass, and wanted to go deeper here specifically on the insurance side of that conversation.
What Are Insurance Basics? Why They Feel Confusing on Purpose
Insurance is one of those products people buy and then quietly hope they never need to think about again. That’s understandable. Nobody wants to spend an afternoon reading through policy language written for lawyers instead of people.
The problem is that the moment insurance matters is usually the worst possible time to be learning how it works. A car accident, a house fire, a health emergency. That’s not the moment to be discovering what your deductible means or realizing your coverage limit was lower than you assumed. Understanding the basics now, while nothing is on fire, is what makes the hard moments easier later.
The Difference Between a Premium and a Deductible
This is one of the first things I walk clients through, because the two terms get confused constantly. A premium is what you pay to keep a policy active, usually monthly or annually. A deductible is what you pay out of pocket before your insurance starts covering a claim.
A lot of people don’t realize these two numbers move in opposite directions. A higher deductible usually means a lower premium, since you’re agreeing to shoulder more of the cost yourself before coverage kicks in. A lower deductible means a higher premium, since the insurance company is taking on more of the risk upfront. Neither option is automatically better. It depends on how much financial cushion you have if something happens.
Types of Insurance Coverage You Actually Need
Not everyone needs every type of insurance, but a few categories come up again and again for the families and individuals I work with in Naples and across Southwest Florida.
Life insurance protects the people who depend on your income if something happens to you. Health insurance covers medical costs, obviously, but the details of what counts as in network versus out of network trip people up constantly. Property insurance, homeowners or renters, protects your physical belongings and the structure itself. And here in Florida specifically, flood insurance is worth a serious conversation, since standard homeowners policies typically don’t cover flood damage at all, something a lot of new residents don’t find out until it’s too late.
I wrote more about how budgeting and financial planning depend on the same kind of consistency that good insurance decisions require. Both come down to understanding your actual risk instead of guessing at it.
What “Coverage Limits” Actually Mean
A coverage limit is the maximum amount your insurance will pay out for a covered claim. This is one of the insurance basics that quietly causes the most financial pain, because people often assume their policy will cover whatever happens, without checking whether the limit matches the value of what they’re protecting.
I’ve seen homeowners find out after a major loss that their coverage limit was set years earlier and never adjusted, even as home values in Naples climbed. Reviewing your coverage limits every year or two, especially after a major purchase or renovation, is a simple habit that prevents a painful surprise later.
Why Bundling Isn’t Always the Best Move
Bundling home and auto insurance with the same provider is common advice, and it can genuinely save money. But it’s not automatically the right call for everyone. Sometimes a specialized provider offers meaningfully better coverage or pricing for one specific policy, and bundling everything under one company just to simplify billing ends up costing more over time.
I’d rather see someone compare their options honestly every few years than assume loyalty to one insurer is automatically saving them money. Insurance basics like this one rarely get mentioned because bundling is convenient to sell, not necessarily because it’s always the smartest financial decision.
How Insurance Basics Affect Your Bigger Financial Picture
Insurance isn’t a separate decision from the rest of someone’s financial life. It’s part of the same picture as budgeting, saving, and long-term planning. The point of insurance is to protect the financial progress you’re already making, so that one unexpected event doesn’t undo years of careful saving.
I explored a related idea in why community matters so much in raising a family, since a strong support system and the right insurance coverage often serve the same purpose. Both exist so that one hard moment doesn’t turn into a lasting setback.
Reviewing Your Policy Doesn’t Require an Expert
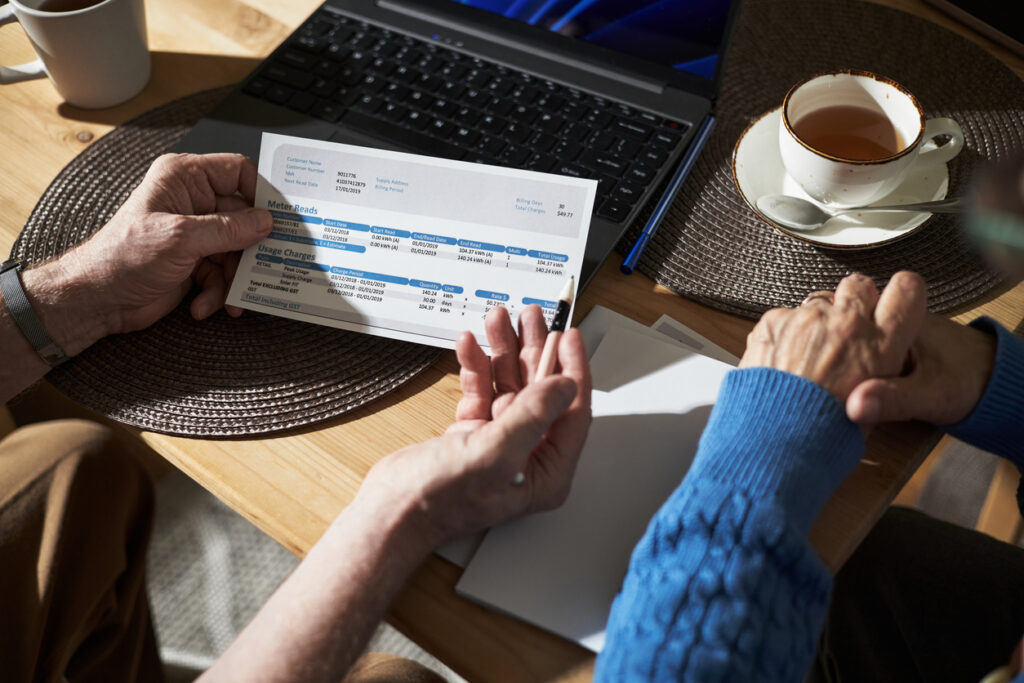
You don’t need an insurance license to understand your own policy. Reading through your declarations page, the summary that lists your coverage types and limits, is a good place to start. If something doesn’t make sense, that’s a normal reaction, not a sign you’re missing something obvious. Ask your agent to explain it in plain language. A good one will.
Key Takeaways on Insurance Basics
Insurance basics don’t require a finance background to understand, and you don’t need to memorize every term in your policy to feel confident about your coverage. What helps most is treating insurance the same way I’d encourage anyone to treat their banking or budgeting, as something worth understanding before you need it, not after.
If there’s one thing I want people in Naples and beyond to take from this, it’s that insurance basics aren’t complicated once someone walks you through them, and understanding them now is one of the simplest ways to protect the life you’re already building.
About Bobby Garon
Bobby Garon is a finance and insurance professional based in Naples, Florida, where he lives with his wife and son. He writes about financial education, leadership, personal growth, family, and community involvement.
Frequently Asked Questions about Insurance Basics
What’s the difference between a premium and a deductible?
A premium is the amount you pay regularly to keep your policy active. A deductible is what you pay out of pocket before your insurance coverage starts paying toward a claim.
How much insurance coverage does someone need?
It depends on individual circumstances, but life, health, and property insurance cover most people’s core needs. In Florida specifically, flood insurance is worth a separate conversation, since it isn’t included in standard homeowners’ policies.
Is bundling home and auto insurance always the best option?
Not necessarily. Bundling can save money, but Bobby Garon recommends comparing providers periodically rather than assuming one company automatically offers the best deal for every policy.
Why do coverage limits matter so much?
A coverage limit is the maximum your policy will pay on a claim. If that limit hasn’t been reviewed in years, it may no longer match the actual value of what’s being insured, especially in a market like Naples where property values change.
Do you need to be a finance expert to understand your own policy?
No. According to Bobby Garon, reading through your policy’s declarations page and asking your agent to explain anything unclear is enough to build real confidence in your coverage.