By Bobby Garon
A retirement paycheck is something most people never think to plan for, even though they’ve been paid on a predictable schedule their entire working life. I talk with a lot of clients here in Naples, Florida who are focused almost entirely on hitting a certain savings number, as if reaching that number is the finish line. In my experience, the number matters less than most people think. What determines whether retirement feels secure is whether you’ve built yourself a retirement paycheck you can count on month after month.
What Is a Retirement Paycheck Strategy?
A retirement paycheck strategy is a plan for converting savings into predictable, ongoing monthly income, rather than withdrawing money without a clear structure behind it. It treats retirement income the way a paycheck once worked during your career: steady, reliable, and planned in advance, instead of something reassembled from scratch every time a bill comes due.
Why a Savings Number Isn’t the Real Goal
I understand the appeal of a target number. It feels concrete, and it gives people something to work toward. The problem is that a large pile of savings doesn’t automatically translate into a plan for turning that money into income you can live on for 20 or 30 years.
Accumulating money and creating income from it are two different things. During your working years, growth is usually the priority. In retirement, the priority shifts toward drawing down what you’ve built in a way that lasts, without pulling too much out too soon or getting caught exposed if the market takes a rough turn right when you need to start withdrawing.
Start With Your Income Floor
Before worrying about investment returns or withdrawal rates, I encourage clients to figure out their income floor first. That’s the amount of money needed each month to cover essential expenses, housing, insurance, food, transportation, along with the lifestyle they’d like to maintain.
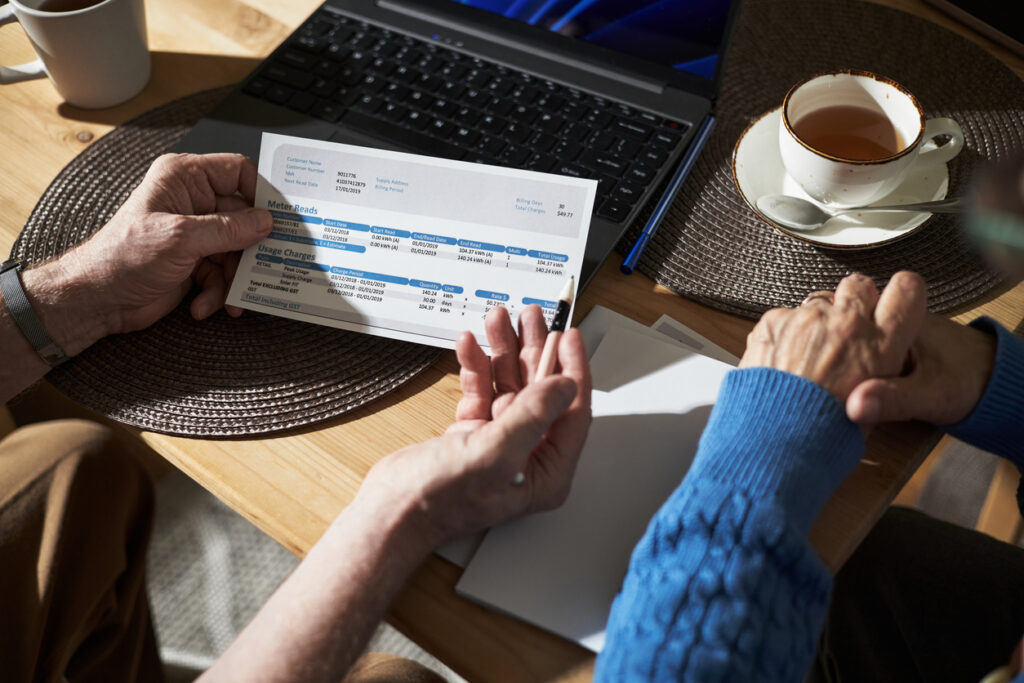
This means looking honestly at what you spend today, then thinking through what might grow in retirement, healthcare costs, more travel, occasional big expenses like a vehicle replacement or a home repair. Once you have a realistic monthly number, compare it against predictable income sources like Social Security, a pension if you have one, and any guaranteed income products. If there’s a gap between what you’ll need and what’s reliably coming in, that gap is what your retirement paycheck strategy needs to solve.
I wrote about a similar kind of groundwork in why budgeting and financial planning go hand in hand. Retirement income planning is really an extension of the same habit, so it is important to understand your numbers and not make decisions based on assumptions.
Building Reliable Income, Not Just a Big Portfolio
A portfolio full of investments, dividend paying stocks, and real estate can absolutely play a role in retirement, but you should not rely on that entirely. Market performance varies and relying on just one portfolio to cover monthly bills can leave you vulnerable during a downturn, especially early in retirement when a bad stretch of returns can do outsized damage to how long the money lasts.
A more dependable approach layers in income you can count on regardless of what the market is doing, Social Security, a pension, and in some cases annuities or other guaranteed income products. When your essential expenses are covered by predictable income, your investment portfolio gets more room to breathe. You’re not forced to sell something at a loss just because the electric bill is due. The portfolio can recover on its own timeline while still funding travel, hobbies, and other similar discretionary expenses.
This is the same logic I laid out in insurance basics everyone should understand. Protecting the essentials first gives you room to take on appropriate risk everywhere else.
Spending Isn’t Flat Throughout Retirement
A lot of retirement plans assume spending stays roughly the same every single year but many new retirees spend more in the early years than they do later. There’s finally time for golf, travel, and the things that got put off during a career. Later, spending patterns often shift as people tend to slow down, meanwhile healthcare and long term care costs can climb.
A retirement paycheck strategy should account for those different stages instead of pretending your spending will look identical at 70 as it did at 60. I think about this the same way I think about risk in what golf has taught me about managing risk. Planning for the whole course, not just the one shot in front of you, tends to produce better outcomes over time.
Don’t Underestimate What Can Quietly Drain Your Savings
Healthcare gets most of the attention as a threat to retirement savings, and it’s a real one. But there’s a quieter risk that catches people off guard just as often, generosity toward family.
Retirees frequently feel obligated to help an adult child with a car, a mortgage shortfall, or an unexpected bill. Helping family is a genuinely good instinct, and I don’t think anyone should feel bad about wanting to do it. But every withdrawal made to help someone else reduces what’s available for your own future, and it’s worth thinking through how many years your savings theoretically need to last before making a significant gift. Protecting your own security isn’t selfish. It’s part of making sure you can keep helping the people you love for years to come, rather than just once.
Building This Takes the Same Patience as Everything Else
Building a retirement paycheck happens through the same kind of patient, steady planning I wrote about in what fatherhood has taught me about patience in business. It’s something that gets built and adjusted over many years, the same way trust gets built with a client one honest conversation at a time.
Key Takeaways on Building a Retirement Paycheck
Before retiring, I’d encourage anyone to ask themselves three specific questions.
- How much will you need each month in retirement?
- How much predictable income will already be coming in during your retirement years?
- And how do you plan to fund whatever gap remains between those two numbers?
Retirement is the one job most people take without knowing exactly how they’ll get paid. Building your own retirement paycheck, deliberately and with a plan for the different stages ahead, is one of the most important things you can do to make sure the money lasts as long as you do.
About Bobby Garon
Bobby Garon is a finance and insurance professional based in Naples, Florida, where he lives with his wife and infant son. His professional experience includes client-facing roles at JPMorgan Chase & Co. and Morgan Stanley, as well as work as a Licensed Commercial and Personal Lines Insurance Advisor at Brown & Brown Insurance. He writes about financial education, leadership, personal growth, family, and community involvement. His work and interviews have appeared on CanvasRebel Magazine and VoyageMIA. His licenses and employment history can be independently verified through FINRA BrokerCheck.
Frequently Asked Questions about Building a Retirement Paycheck
What is a retirement paycheck strategy?
It’s a plan for turning savings into predictable, ongoing income during retirement, rather than simply withdrawing money without a clear structure behind it.
Why isn’t hitting a savings number enough on its own?
A large savings balance doesn’t automatically create reliable income. Building an actual paycheck requires a plan for how and when that money gets distributed over decades.
What is an income floor?
An income floor is the amount needed each month to cover essential expenses. Comparing this number against predictable income sources shows whether there’s a gap that needs to be addressed before retiring.
Does retirement spending stay the same every year?
No. Spending often runs higher in early retirement due to travel and new free time, then shifts later as healthcare and long-term care costs become more significant.
What’s an overlooked risk to retirement savings?
Generosity toward adult children or family members is a common one. Helping family is admirable, but every withdrawal reduces what’s available for your own future, so it’s worth planning those gifts carefully.